Drawdown analysis
Maximum drawdown, average recovery time, and drawdown distribution across calendar years — so you understand the worst realistic losing streak your account should be sized to absorb.
Backtesting
Our backtesting service runs your logic against tick-level historical data and delivers a full performance report — before you risk any capital.
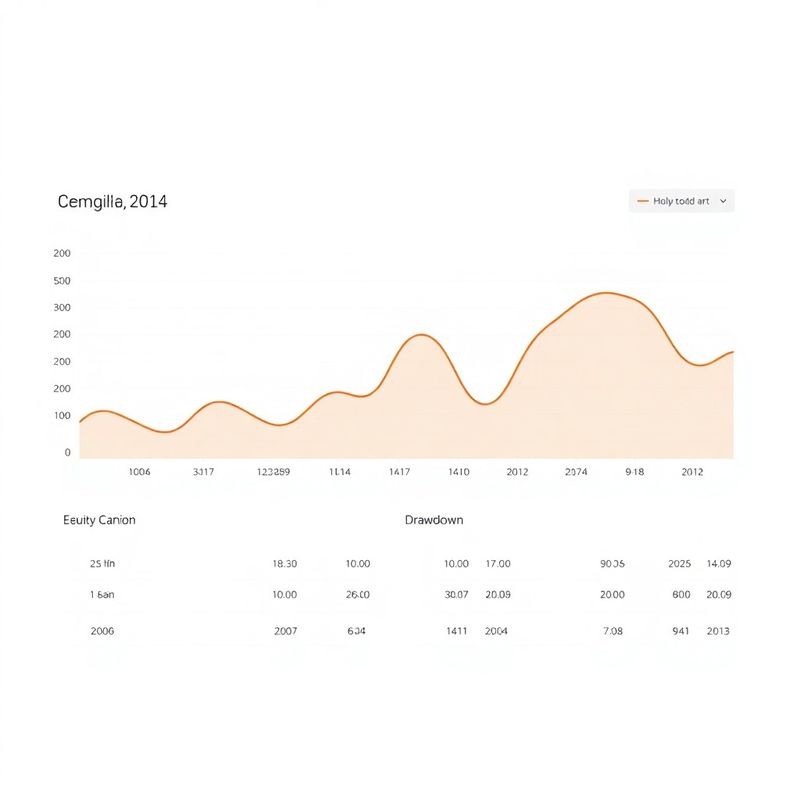
A strategy that looks compelling on a handful of recent trades can fall apart when tested across different volatility regimes, seasonal patterns, and flash-crash events. Rigorous backtesting doesn't guarantee future results — no tool can — but it does reveal structural weaknesses: over-optimised parameters, excessive drawdown in 2020-style conditions, or a Sharpe ratio that depends entirely on three lucky months. At Sterling Atelier we run backtests on data sourced from exchange-grade tick feeds, not resampled OHLC approximations, so the fill simulation is as close to reality as possible.
Numbers that tell you the truth, not the story you want to hear.
Maximum drawdown, average recovery time, and drawdown distribution across calendar years — so you understand the worst realistic losing streak your account should be sized to absorb.
Risk-adjusted return metrics calculated on the actual trade series, not annualised from a monthly average. We include a Monte Carlo simulation to estimate the range of plausible live outcomes.
Broker spreads, commissions, and realistic slippage estimates are baked into every backtest. You see net-of-costs results, not the gross figures that make strategies look better than they are.
Tests span a minimum of three years by default, covering at least one high-volatility and one low-volatility period. Longer histories are available for instruments with sufficient tick data.
The backtest report revealed that my breakout strategy had a catastrophic drawdown in Q1 2020 that I'd never seen in my short live history. Sterling Atelier's slippage modelling was sobering but exactly what I needed before scaling up.
Mihaela T., prop trader, Bucharest
Send us your rules and we'll deliver a full report within five business days.
Request a backtest